A calm guide to protecting your home before a tropical storm or hurricane arrives, and knowing exactly what to do if water gets in after.
Storm forecasts change by the hour. For the current watches, warnings and life-safety guidance for your area, always follow the National Hurricane Center, your local National Weather Service office, and your state and county emergency management agencies.
Every hurricane season, storms that form in the Atlantic and the Gulf turn toward the East Coast. Some make landfall on the Carolina coast. Many more come ashore somewhere else and then track north and inland as tropical storms or their remnants, dragging days of rain across North Carolina, Virginia, Washington DC, Maryland and Pennsylvania. You do not have to live on the coast for a hurricane to reach your house. Inland flooding from heavy rain is one of the biggest causes of damage from these storms, well away from the beach.
That is genuinely useful to know, because rain is something you can prepare for. Being outside a storm’s direct path is good news, and it is not the same as “nothing to do here.” Preparing well before the rain is what makes the difference if water does find its way in.
Rescue One Restoration is a booking service: when water gets in, we book a licensed local restoration pro who covers your address. This guide is built for two moments: the hours before the rain, when a little preparation goes a long way, and the hours after, when you find water where it shouldn’t be. Read the first half before the storm. Bookmark the second half in case you need it.
Before the storm: protect your home while it’s still dry
The most useful work happens before a drop falls. None of it requires climbing on a roof or heading outside once conditions turn. Do these while the weather is calm and daylight is on your side.
Clear the paths water is supposed to take
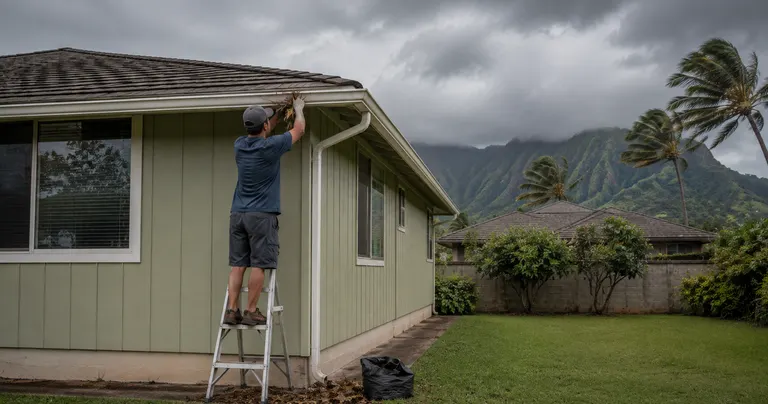
Gutters, downspouts, and yard drains only help if they’re clear, and autumn leaves arrive with the back half of hurricane season. A downspout choked with leaves sends roof runoff straight down against your foundation instead of away from it. Walk the perimeter, clear what you can safely reach, and make sure downspout extensions actually carry water a few feet out from the house. If you have a basement window well or a sump pump, check that the well is clear and test the pump by pouring a bucket of water into the pit.
Move what matters up and off the floor
Electronics, important documents, photo albums, and anything irreplaceable should come up off ground level: onto shelves, into higher closets, or into sealed bins. Family heirlooms and papers are the things people grieve most after a flood, and they’re the easiest to protect in ten minutes today. If you have a basement, garage or ground-floor room that has taken on water before, treat it as the likeliest entry point and clear it first.
Photograph every room now: your insurance claim starts before the storm
This is the single most valuable thing you can do, and almost nobody does it. Walk through your home with your phone and take dated video and photos of every room, including the contents of closets and cabinets. This is your pre-loss record. If you ever have to file a claim, being able to show an adjuster exactly what a room looked like, and what was in it, before the water arrived removes most of the argument about what was damaged. It is nearly impossible to recreate after the fact, and it costs you nothing but a few minutes. Store the footage somewhere other than your phone: a cloud account or an email to yourself works.
Know where water gets in
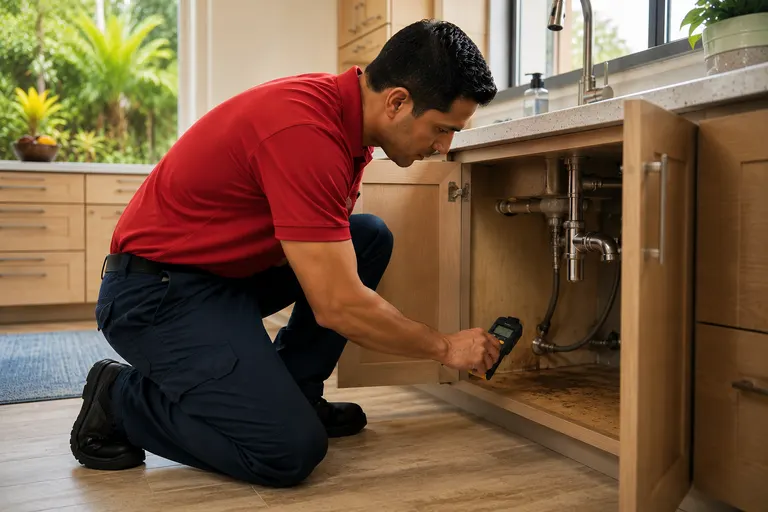
Every house has weak points. Basement walls and windows, sliding and patio door thresholds, garage doors, chimney flashing and older single-pane windows are common ones. Wind-driven rain finds gaps that ordinary rain never touches. Knowing your home’s weak points tells you where to lay towels or sandbags now, and where to look first if you’re checking for water later.
For a broader prep checklist that goes beyond water, the federal government’s Ready.gov hurricane guidance covers supplies, communication plans and evacuation basics.
During the storm: follow the officials, not us
Once the weather turns, life safety is the only priority, and the people to listen to are the emergency management professionals, not a restoration company or a booking service. We do not advise on evacuation, sheltering, or whether it’s safe to enter or stay in a structure. Those calls belong to the National Weather Service and your state and county emergency management agencies.
Stay inside, stay away from flooded roads and standing water (most flood deaths happen in vehicles), and keep your phone charged and within reach for emergency alerts. Property can be dealt with afterward. Your safety and your family’s cannot be replaced. When conditions have passed and officials say it’s safe, the section below is what to do next.
After the storm: what to do when you find water inside
If you come back to water where it shouldn’t be, the order you do things in matters, both for your safety and for your insurance claim.
Step 1: Make sure it’s safe before you go in
Only enter or inspect once officials have said the area is safe. Standing water can hide electrical hazards, and saturated ceilings and walls can be unstable. If water is anywhere near outlets, panels or appliances, keep the power off to that area and stay out until you’re sure. A flooded basement with a furnace, water heater or electrical panel in it is a job for the utility or an electrician first. When in doubt, wait.
Step 2: Stop or slow the source if you safely can
If the water is coming from a plumbing failure rather than the storm, a burst supply line or an overflowing fixture, shut off the water at the main to stop it getting worse. For storm-driven water coming through the roof, windows or basement walls, there may be nothing to safely shut off, and that’s fine; move to documenting.
Step 3: Document everything before you move anything
Before you mop, move furniture or throw anything away, photograph and video it. Capture the standing water, the affected flooring and walls, and any damaged belongings. Do not discard damaged property until it has been documented and, ideally, seen by your adjuster. This record is what turns a disputed claim into a straightforward one.
Step 4: Start removing water and moving air where it’s safe
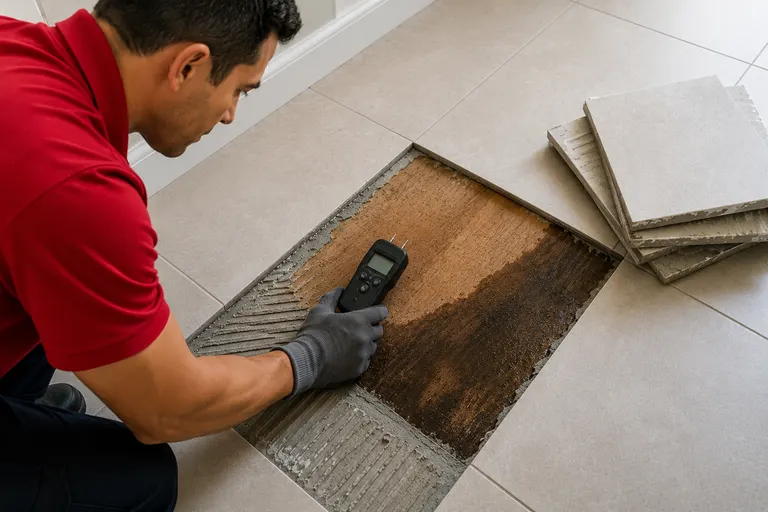
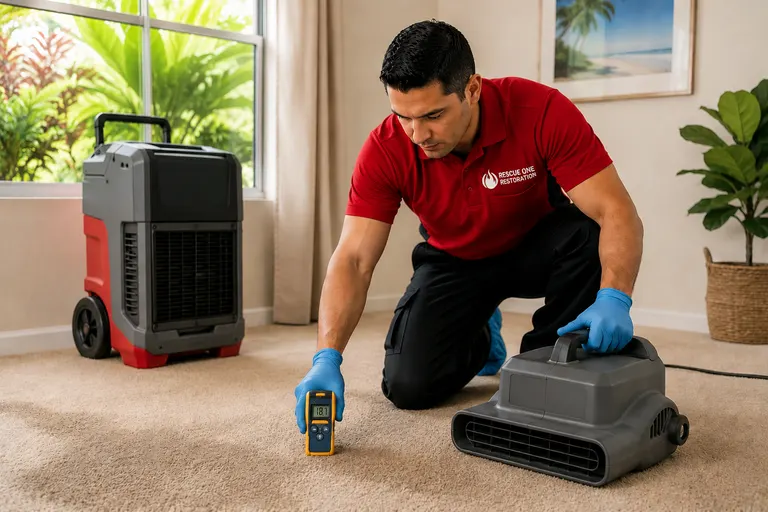
Once you’ve documented the scene, you can begin removing standing water and improving airflow in the areas that are safe to work in. Household fans and a shop vac help at the margins, but understand their limits: surface water is the visible part of the problem. Water wicks into drywall, subfloor and insulation, and that hidden moisture is what drives the real damage. Professional extraction and structural drying exist because towels and box fans can’t reach it.
Step 5: Get help before the mold window closes
Late-summer and early-autumn storms arrive in the warmest, most humid weeks of the year. In those conditions, wet building materials can begin growing mold within roughly 24 to 48 hours. The drywall and insulation that soaked up floodwater are exactly what mold feeds on, and once it takes hold, a drying job becomes a remediation job. That’s the clock that matters after the water is in. If you’d like a professional set of eyes and equipment on it, request service online any time and we book a licensed local restoration pro. For the fuller picture, read what to do after flood damage.
The insurance question: is storm water damage covered?
This is where homeowners get caught, so it’s worth understanding before you file. The short version: how the water got in usually matters more than the fact that there’s water. The coverage itself comes down to your policy and the cause of loss. This is general information, not insurance or legal advice. Confirm your policy specifics with a licensed agent or your carrier before relying on any of it.
Wind-driven rain versus rising water
As a general rule, damage from wind-driven rain that enters through a storm-created opening, say wind tears off a section of roof and rain pours in, is often addressed under a standard homeowners policy, sometimes with a separate wind or hurricane deductible in coastal areas. Damage from water that rises up from the ground, surface flooding, storm surge, an overflowing creek or river, typically is not covered by a standard homeowners policy and instead falls under separate flood insurance, usually through the National Flood Insurance Program (NFIP). Water that seeps through basement walls or backs up through a floor drain is its own category again, and often needs a specific endorsement. The distinctions are real and they are where claims are won or lost.
What the pro handles, and what stays with you
Many restoration pros work directly with your insurance company and document the loss, moisture readings, photos and drying logs, to the standard adjusters recognize. What stays with you is the policy relationship: confirming your coverage and deductible, and reporting the claim to your carrier. If you’re unsure which category your damage falls into, that’s a normal thing to talk through with your agent. Read more about flood damage restoration.
If water gets in, act while it still counts
Most storms spare most homes the worst, but “likely” isn’t “certainly,” and the heavy rain a tropical system drags inland is enough to flood a home on its own. The preparation you do beforehand, clearing drains, lifting valuables, photographing your rooms, is what makes the aftermath manageable if the water does come.
And if it does, remember the clock. Once officials say it’s safe and you’ve documented the damage, the sooner drying begins, the more of your home you keep. Request service and we book a licensed local restoration pro who works with your insurance company from the first walkthrough, so you can focus on your family.
Stay safe. Follow the officials for anything involving your safety, and keep this page handy in case you need the second half of it.